Category Archives: Uncategorized

Buying Bank Auction Property in India: Benefits, Risks and Legal Due Diligence

Buying property through a bank auction has emerged as an attractive alternative to conventional real estate transactions in India. Banks and financial institutions recover outstanding loans through auctions under the SARFAESI Act, 2002, offering prospective buyers opportunities to acquire residential, commercial and industrial properties at competitive prices. For investors, entrepreneurs and individuals seeking their own homes, these auctions provide an avenue for prudent investment. With proper financial planning and legal diligence, buyers can unlock valuable real estate opportunities while avoiding unnecessary complications.

Why Buying Auction Property Can Be a Rewarding Investment

One of the principal advantages of purchasing auction property is the possibility of acquiring real estate below its prevailing market value. Banks primarily seek recovery of outstanding dues rather than maximising property appreciation, making certain assets available at attractive reserve prices. This may provide buyers with immediate investment potential. Furthermore, institutional auctions follow prescribed procedures involving sale notices, reserve prices and bidding mechanisms, offering a structured framework for property acquisition. Gaurav Goel, Senior Partner, Supreme Laws, observes, “Bank auctions can create significant opportunities for genuine property buyers. A carefully evaluated asset acquired at a competitive price can deliver substantial long-term value while supporting the efficient recovery of financial assets.”

Another advantage lies in the diversity of available properties. Bank auctions may include residential flats, independent houses, commercial establishments, industrial units and land parcels. Buyers can choose assets according to their financial capacity and investment objectives. Residential properties may provide opportunities for personal occupation or rental income, while commercial assets can support business expansion and capital appreciation. Completed properties may also reduce certain uncertainties associated with under-construction projects, including construction delays and changes in specifications. With appropriate selection, auction properties can become a valuable component of a diversified real estate portfolio.

The institutional nature of bank auctions provides additional practical benefits. The lending institution generally possesses mortgage-related documentation, and the sale follows an established legal process. Advocate Tarlok Singh, SARFAESI Expert, remarks, “The SARFAESI auction mechanism offers an organised avenue for property acquisition. Buyers who understand the prescribed procedure and evaluate the asset carefully can benefit from opportunities that may not be readily available in conventional transactions.” Competitive bidding further enables participants to determine the acquisition price, potentially creating opportunities for rental returns and long-term wealth generation.

Legal and Financial Checks Before Bidding

Despite these advantages, auction properties require careful scrutiny. Sale notices frequently contain the expression “as is where is, as is what is and whatever there is,” placing considerable importance on independent verification. Buyers should examine title documents, encumbrance records, municipal approvals, property taxes, pending litigation and possession status. Outstanding utility charges, society dues, structural defects, unauthorised construction or occupation by previous owners may affect the property’s value and usability. Symbolic possession should not be confused with vacant physical possession.

Financial preparedness is equally important. Successful bidders must comply with prescribed payment timelines, failing which deposits may be forfeited and sales cancelled. Pending proceedings before the Debt Recovery Tribunal or other competent authorities should also be investigated. Gaurav Goel cautions, “An attractive reserve price should never substitute for legal due diligence. Buyers must evaluate title, possession, liabilities and the total acquisition cost before placing a bid.” Stamp duty, registration charges, renovation expenses and possession-related costs must be included in the investment budget.

Bank auctions offer genuine opportunities for affordable property acquisition, diversified investment and long-term appreciation. However, successful participation requires informed decision-making rather than price-driven enthusiasm. Independent legal verification, financial preparedness and a clear understanding of auction conditions remain essential. With the right balance of opportunity and caution, bank auction properties can serve the interests of buyers, investors and the banking sector while strengthening India’s real estate market.

Editorial note: The expert comments above are drafted for approval and attribution; please obtain confirmation from Gaurav Goel and Advocate Tarlok Singh before publishing them as direct quotations.
Why Competent Legal Representation Matters in Resolving Legal Disputes

A legal dispute can emerge without warning and may affect a person’s property, finances, relationships, reputation or business interests long after a court hearing has concluded. Matters involving property, matrimonial issues, commercial transactions, employment, criminal allegations, contractual obligations or monetary claims often require much more than a basic understanding of the law. Litigation is governed by procedural rules, limitation periods, evidentiary requirements, pleadings and judicial precedents, and overlooking any of these aspects can affect the manner in which a case progresses. Professional legal representation enables a litigant to understand the available legal remedies, identify the issues that require attention and take decisions based on the applicable law and facts. The advocate’s role therefore extends beyond arguing before a court. It includes analysing the dispute, examining the available material, advising the client and ensuring that the case is presented in accordance with the relevant legal framework. The legal-services system in India also recognises the importance of legal advice and representation as part of meaningful access to justice.

Gaurav Goel, Senior Partner at Supreme Laws, places particular emphasis on preparation, clarity and a well-defined strategy while dealing with litigation. A legal matter, from this perspective, should not be approached merely as a sequence of court appearances. The first step is to understand what the client seeks to achieve, study the relevant documents and separate the important factual and legal questions from peripheral issues. Such an approach can assist in framing appropriate pleadings, identifying the material evidence and avoiding procedural or strategic mistakes. Timeliness is another critical consideration. Legal proceedings frequently operate within prescribed periods, and delay in filing a proceeding, challenging an order or taking a required procedural step may adversely affect the remedies available to a party. As Gaurav Goel explains, a structured approach based on preparation and strategic planning can make the handling of a legal dispute more effective and focused.

Advocate Tarlok Singh observes, “Effective legal representation begins with understanding the client’s concerns, examining the facts carefully and developing a legal strategy suited to the circumstances of the case. A lawyer’s responsibility is not merely to appear before the court, but to ensure that the client’s lawful interests are presented with clarity, preparation and diligence.” This approach underlines why legal advice cannot ordinarily be reduced to a standard formula applicable to every dispute. Two matters may appear similar at first glance but can require entirely different remedies because of differences in documents, facts, jurisdiction, limitation or applicable statutory provisions. An advocate may therefore need to examine the complete factual background, scrutinise supporting material, identify relevant legislation and consider judicial precedents before advising the client on the appropriate course. Depending upon the circumstances, the available route may involve negotiation, mediation, arbitration, civil litigation, criminal proceedings, an appeal or a constitutional remedy. Selecting the legally appropriate forum and remedy is consequently an important part of effective representation.

Gaurav Goel also highlights the importance of identifying legal risks before they mature into contentious proceedings. Preventive legal advice can be particularly valuable when individuals or businesses enter into contracts, undertake financial transactions or create arrangements involving significant rights and obligations. Clear drafting can define the responsibilities of the parties, reduce uncertainty and provide mechanisms for addressing future disagreements. Once litigation begins, however, the advocate’s responsibilities become broader and may include drafting and revising pleadings, compiling documentary and oral evidence, responding to applications, monitoring procedural developments, evaluating settlement opportunities and advancing arguments supported by law and evidence. Effective representation is therefore a continuing process rather than an isolated courtroom exercise. It requires the lawyer to remain attentive to both the legal position and the practical objectives of the client while ensuring that every step is supported by the available facts and applicable law.

Competent legal representation ultimately enables a person to approach a dispute with greater legal awareness and a clearer understanding of the options available. An advocate can assist in identifying the strengths and weaknesses of a matter, explaining potential remedies, complying with procedural requirements and presenting the client’s lawful case before the appropriate forum. At the same time, effective representation depends upon the client providing complete and truthful information and making relevant documents available to counsel at the earliest opportunity. Seeking advice at an early stage may also allow legal risks to be addressed before they develop into prolonged disputes. For individuals who satisfy the applicable eligibility requirements, India’s legal-services framework additionally provides avenues for obtaining free legal aid, including legal representation. In a system where evidence, procedure, jurisdiction and limitation can significantly influence the progress of a case, competent legal assistance can help individuals and organisations pursue their legal rights and remedies in a more informed, organised and responsible manner.

What to Do Immediately After a Crash and How to Deal With Insurance?

A road accident is often followed by confusion, panic and uncertainty about what should be done first. In such a situation, the immediate priority is to protect life and prevent further harm. If anyone is injured, medical assistance should be called without delay and the injured person should be taken to a hospital as appropriate. Once immediate safety has been addressed, the accident scene should be documented as carefully as possible. Photographs and videos of the damaged vehicles, position of the vehicles, road conditions, traffic signals, skid marks and visible injuries can later become valuable evidence. The registration number and contact details of the other vehicle’s driver should also be recorded, along with details of people who witnessed the accident. Gaurav Goel, Senior Partner, Supreme Laws, says: “The first few minutes after an accident can determine the quality of evidence available later. People should concentrate not only on the damage to their vehicle but also on preserving facts that may establish how the accident actually occurred.”

The accident should then be reported to the appropriate authorities, particularly where there are injuries, substantial damage, a dispute regarding fault or circumstances suggesting negligent or dangerous driving. A police complaint or FIR, where appropriate, may become important in establishing the circumstances of the accident. At the same time, the vehicle owner should inform the insurance company through the prescribed claim procedure and obtain a claim or reference number. It is advisable to keep a separate record of every interaction with the insurer, including emails, messages, inspection details and documents submitted. The policyholder should also preserve the insurance policy, registration certificate, driving licence, repair estimates, photographs and medical papers. Gaurav Goel, Senior Partner, Supreme Laws, adds: “An insurance claim is not merely a conversation with the insurer; it is a documented legal process. A claimant who maintains a proper paper trail is in a much stronger position if the claim later becomes contentious.”

The vehicle should ordinarily be made available for inspection or assessment before extensive repairs are carried out, particularly where the insurer requires a survey or inspection under the applicable policy terms. The policyholder should provide truthful information and the documents reasonably required for assessment of the loss. At the same time, the claimant should not blindly accept the insurer’s assessment. The policy should be examined to understand the scope of coverage, deductibles, depreciation, exclusions and other applicable conditions. If the insurer proposes a settlement amount, the claimant should carefully examine how that figure has been calculated. Advocate Tarlok Singh explains: “The amount offered by an insurance company should be examined against the actual policy coverage and the documented loss. If there is a disagreement, the policyholder should ask for the basis of the assessment and preserve the survey and settlement documents rather than relying on oral discussions.”

If an insurance claim is rejected, delayed or settled for an amount that the policyholder believes is unjustified, the matter should not simply be abandoned. The claimant should request the insurer to communicate its decision and reasons in writing. A proper review of the policy, claim documents, survey report, photographs, repair bills and correspondence can help determine whether the insurer’s position is sustainable. Where necessary, the policyholder can pursue the insurer’s internal grievance mechanism and thereafter explore the remedies available under the applicable insurance and consumer law framework. In serious accidents involving bodily injury or death, there may also be separate claims for compensation arising from the accident. Such proceedings can involve questions of negligence, contributory negligence, insurance coverage and the appropriate assessment of compensation. Legal advice at an early stage can therefore help prevent avoidable mistakes, particularly where the parties disagree about fault or the insurer contests the claim.

After a crash, act promptly but do not act carelessly. Secure medical help, preserve the accident scene, collect reliable evidence, inform the police where appropriate, notify the insurer and maintain copies of every document. Do not admit liability merely because you are shaken or pressured at the scene, and do not sign a final settlement document without understanding its consequences. Where injuries are serious, liability is disputed or an insurance claim is rejected or inadequately assessed, timely legal assistance can be crucial. The strongest accident claim is usually built not after the dispute begins, but from the evidence preserved immediately after the accident.

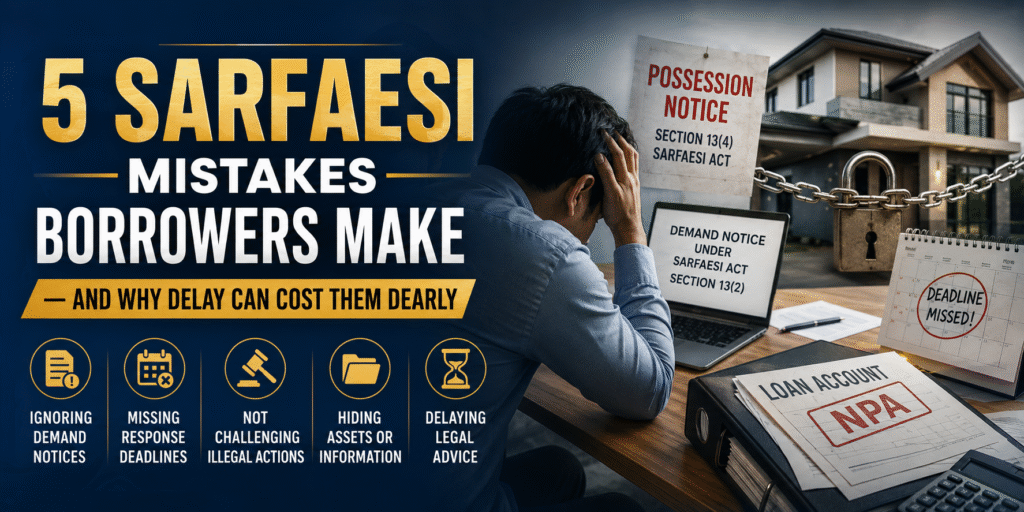
5 SARFAESI Mistakes Borrowers Make — And Why Delay Can Cost Them Dearly

When a borrower receives a SARFAESI notice, the first reaction is often emotional rather than legal: “The bank cannot take my property.” That assumption can be costly. The SARFAESI Act gives secured creditors a statutory route for enforcing security interests, while also providing borrowers with specific opportunities and remedies at different stages of the process. One of the biggest mistakes borrowers make is therefore ignoring the first demand notice. A Section 13(2) notice should not be treated as routine correspondence. It is the point at which the borrower should verify the outstanding amount, examine the loan account, check the security documents and identify any genuine dispute concerning the bank’s claim. A borrower who waits for possession or auction before taking advice may find that valuable time has already been lost.

The second mistake is responding emotionally instead of responding intelligently. A letter saying that the borrower is suffering financial hardship or requesting the bank to “give some more time” may not address the actual legal or factual issues in the account. If there are genuine discrepancies, they should be supported with documents and clearly presented. The third mistake is assuming that a technical defect automatically wipes out the bank’s entire claim. It does not. A borrower may identify an irregularity in possession, valuation or sale proceedings, but that does not necessarily mean the underlying debt has disappeared. The enforcement process has to be examined as a whole, including compliance with the Security Interest (Enforcement) Rules, which prescribe requirements concerning possession notices, valuation, reserve price and sale of immovable secured assets.

The fourth mistake is waiting until the property is advertised for auction before exploring legal remedies. Once possession and sale formalities have progressed, the borrower may have to act quickly and within the applicable statutory framework. Section 17 provides a remedy before the Debts Recovery Tribunal against measures taken under Section 13(4). At the same time, borrowers should carefully distinguish between a genuine legal challenge and an attempt merely to postpone repayment. Gaurav Goel, Senior Partner, Supreme Laws, says: “A borrower should not mistake the availability of a legal remedy for a licence to ignore a genuine financial liability. Where the bank has followed the prescribed procedure, the borrower must have a substantive and legally sustainable basis for opposing enforcement.” He further cautions that litigation without a realistic strategy can sometimes reduce the borrower’s options rather than improve them.

The fifth mistake is failing to think about resolution alongside litigation. A borrower may have a legitimate objection to a particular enforcement step and still need to address the underlying financial liability. Depending upon the facts, discussions concerning repayment, restructuring or a negotiated settlement may therefore deserve consideration alongside appropriate legal proceedings. From the bank’s perspective, recovery of secured dues is not merely an administrative exercise; it is the enforcement of a contractual and statutory right, subject to compliance with law. The Rules require, among other things, valuation by an approved valuer and fixation of a reserve price before sale of an immovable secured asset. Gaurav Goel adds: “Banks cannot be expected to keep recovery proceedings indefinitely in abeyance when public or institutional funds remain outstanding. A borrower who genuinely wants to protect the property should act early, place a credible proposal before the lender where appropriate, and pursue only those legal objections that can withstand scrutiny.” The practical lesson is simple: do not ignore SARFAESI, do not rely solely on technicalities, and do not wait until the auction date to decide what to do.


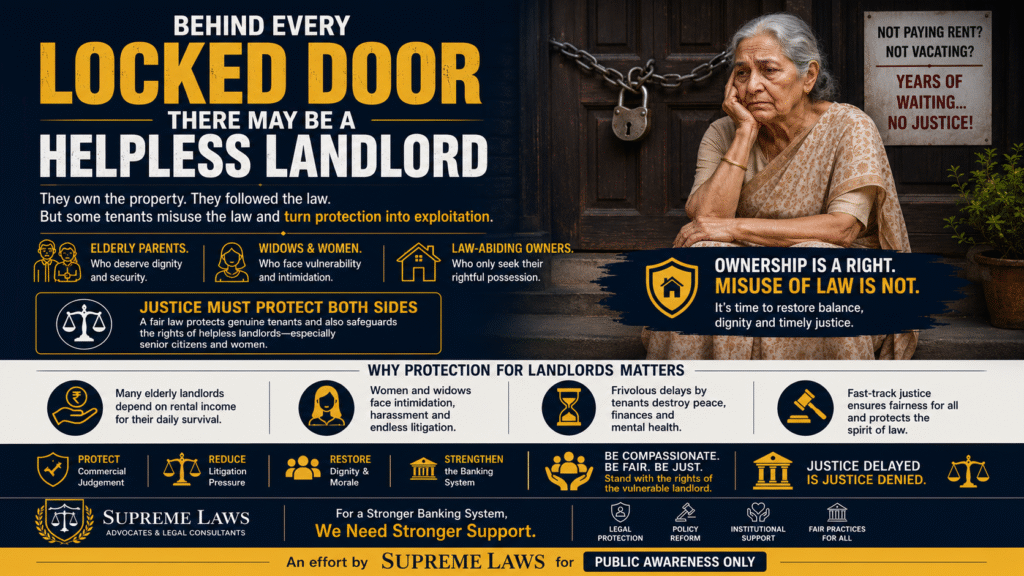
The Forgotten Victims in Rent Disputes: Elderly and Women Landlords Deserve Equal Justice

For decades, India’s tenancy laws have rightly sought to protect tenants from arbitrary eviction and unfair treatment. However, this noble objective has also created an unintended consequence. Across the country, countless elderly parents, widows, and single women who own residential or commercial property are finding themselves trapped in lengthy legal battles simply to recover possession of their own premises. While tenant protection remains an essential pillar of social justice, the law must also recognize that landlords can be equally vulnerable.

Many senior citizens depend entirely on rental income to meet their daily expenses or require their property for personal occupation after retirement. Unfortunately, some tenants misuse legal procedures by withholding rent, refusing to vacate, and prolonging litigation for years. Gaurav Goel, Senior Partner, Supreme Laws, observes, “The law must distinguish between protecting a genuine tenant and rewarding deliberate misuse of legal safeguards. The constitutional right to own and enjoy property cannot be defeated through endless procedural delays, particularly when the landlord is an elderly person or a woman in genuine need.” Justice loses its meaning when the rightful owner spends years fighting merely to use what already belongs to them.

The financial and emotional burden of such disputes is often unbearable. Elderly landlords frequently exhaust their savings on litigation, while widows and women living alone are compelled to endure unnecessary stress and uncertainty. In many cases, these individuals are not wealthy investors but ordinary citizens whose property represents their life’s earnings. When legal proceedings become excessively prolonged, the hardship extends far beyond financial loss—it affects dignity, security, and peace of mind.

Indian courts have consistently recognized that tenancy does not confer ownership and that a landlord’s bona fide requirement deserves legal protection. Advocate Tarlok Singh states, “A tenancy is a contractual relationship, not a permanent right over another person’s property. The legal system must ensure that vulnerable landlords are not compelled to sacrifice their rights because of avoidable procedural delays.” A legal framework that protects both tenants and landlords with equal fairness strengthens public confidence and promotes responsible tenancy rather than conflict.

The need of the hour is a balanced approach. Genuine tenants must continue to receive protection against arbitrary eviction, but habitual defaulters and those who misuse legal provisions should not be permitted to exploit the justice delivery system. Expedited proceedings for disputes involving senior citizens and women landlords, stricter enforcement of eviction orders, and deterrence against frivolous litigation would help restore the equilibrium that tenancy laws originally intended to achieve. As Gaurav Goel, Senior Partner, Supreme Laws, aptly remarks, “Protecting vulnerable landlords is not contrary to tenant welfare. A fair legal system safeguards lawful possession, discourages abuse of process, and ensures that justice is delivered within a reasonable time.”

A compassionate legal system cannot afford to recognize vulnerability only on one side of a dispute. The elderly father waiting to return to his own house, the widow relying on rental income for survival, and the woman seeking possession of her inherited property deserve the same protection that the law extends to tenants. Justice is truly meaningful only when it safeguards both the right to shelter and the right to peaceful ownership, ensuring that neither is sacrificed at the cost of the other.


Disclaimer

As per the rules of the Bar Council of India, we are not permitted to solicit work or advertise in any manner. By proceeding further and clicking on “I Accept” below, the user acknowledges that the transmission, receipt or use of the information on our website does not tantamount to solicitation, advertisement, inducement or personal communication of any sort for and on behalf of the Firm so as to create an attorney-client relationship.

The information provided herein should not be interpreted as legal advice, for which the user must make independent inquiries. Whilst every effort has been taken to ensure the accuracy of the contents of this website, Supreme Laws disclaims all liability arising from reliance placed by the user or any other third party on the information contained therein.