Author Archives: supremelaws

Why Competent Legal Representation Matters in Resolving Legal Disputes

A legal dispute can emerge without warning and may affect a person’s property, finances, relationships, reputation or business interests long after a court hearing has concluded. Matters involving property, matrimonial issues, commercial transactions, employment, criminal allegations, contractual obligations or monetary claims often require much more than a basic understanding of the law. Litigation is governed by procedural rules, limitation periods, evidentiary requirements, pleadings and judicial precedents, and overlooking any of these aspects can affect the manner in which a case progresses. Professional legal representation enables a litigant to understand the available legal remedies, identify the issues that require attention and take decisions based on the applicable law and facts. The advocate’s role therefore extends beyond arguing before a court. It includes analysing the dispute, examining the available material, advising the client and ensuring that the case is presented in accordance with the relevant legal framework. The legal-services system in India also recognises the importance of legal advice and representation as part of meaningful access to justice.

Gaurav Goel, Senior Partner at Supreme Laws, places particular emphasis on preparation, clarity and a well-defined strategy while dealing with litigation. A legal matter, from this perspective, should not be approached merely as a sequence of court appearances. The first step is to understand what the client seeks to achieve, study the relevant documents and separate the important factual and legal questions from peripheral issues. Such an approach can assist in framing appropriate pleadings, identifying the material evidence and avoiding procedural or strategic mistakes. Timeliness is another critical consideration. Legal proceedings frequently operate within prescribed periods, and delay in filing a proceeding, challenging an order or taking a required procedural step may adversely affect the remedies available to a party. As Gaurav Goel explains, a structured approach based on preparation and strategic planning can make the handling of a legal dispute more effective and focused.

Advocate Tarlok Singh observes, “Effective legal representation begins with understanding the client’s concerns, examining the facts carefully and developing a legal strategy suited to the circumstances of the case. A lawyer’s responsibility is not merely to appear before the court, but to ensure that the client’s lawful interests are presented with clarity, preparation and diligence.” This approach underlines why legal advice cannot ordinarily be reduced to a standard formula applicable to every dispute. Two matters may appear similar at first glance but can require entirely different remedies because of differences in documents, facts, jurisdiction, limitation or applicable statutory provisions. An advocate may therefore need to examine the complete factual background, scrutinise supporting material, identify relevant legislation and consider judicial precedents before advising the client on the appropriate course. Depending upon the circumstances, the available route may involve negotiation, mediation, arbitration, civil litigation, criminal proceedings, an appeal or a constitutional remedy. Selecting the legally appropriate forum and remedy is consequently an important part of effective representation.

Gaurav Goel also highlights the importance of identifying legal risks before they mature into contentious proceedings. Preventive legal advice can be particularly valuable when individuals or businesses enter into contracts, undertake financial transactions or create arrangements involving significant rights and obligations. Clear drafting can define the responsibilities of the parties, reduce uncertainty and provide mechanisms for addressing future disagreements. Once litigation begins, however, the advocate’s responsibilities become broader and may include drafting and revising pleadings, compiling documentary and oral evidence, responding to applications, monitoring procedural developments, evaluating settlement opportunities and advancing arguments supported by law and evidence. Effective representation is therefore a continuing process rather than an isolated courtroom exercise. It requires the lawyer to remain attentive to both the legal position and the practical objectives of the client while ensuring that every step is supported by the available facts and applicable law.

Competent legal representation ultimately enables a person to approach a dispute with greater legal awareness and a clearer understanding of the options available. An advocate can assist in identifying the strengths and weaknesses of a matter, explaining potential remedies, complying with procedural requirements and presenting the client’s lawful case before the appropriate forum. At the same time, effective representation depends upon the client providing complete and truthful information and making relevant documents available to counsel at the earliest opportunity. Seeking advice at an early stage may also allow legal risks to be addressed before they develop into prolonged disputes. For individuals who satisfy the applicable eligibility requirements, India’s legal-services framework additionally provides avenues for obtaining free legal aid, including legal representation. In a system where evidence, procedure, jurisdiction and limitation can significantly influence the progress of a case, competent legal assistance can help individuals and organisations pursue their legal rights and remedies in a more informed, organised and responsible manner.
What to Do Immediately After a Crash and How to Deal With Insurance?

A road accident is often followed by confusion, panic and uncertainty about what should be done first. In such a situation, the immediate priority is to protect life and prevent further harm. If anyone is injured, medical assistance should be called without delay and the injured person should be taken to a hospital as appropriate. Once immediate safety has been addressed, the accident scene should be documented as carefully as possible. Photographs and videos of the damaged vehicles, position of the vehicles, road conditions, traffic signals, skid marks and visible injuries can later become valuable evidence. The registration number and contact details of the other vehicle’s driver should also be recorded, along with details of people who witnessed the accident. Gaurav Goel, Senior Partner, Supreme Laws, says: “The first few minutes after an accident can determine the quality of evidence available later. People should concentrate not only on the damage to their vehicle but also on preserving facts that may establish how the accident actually occurred.”

The accident should then be reported to the appropriate authorities, particularly where there are injuries, substantial damage, a dispute regarding fault or circumstances suggesting negligent or dangerous driving. A police complaint or FIR, where appropriate, may become important in establishing the circumstances of the accident. At the same time, the vehicle owner should inform the insurance company through the prescribed claim procedure and obtain a claim or reference number. It is advisable to keep a separate record of every interaction with the insurer, including emails, messages, inspection details and documents submitted. The policyholder should also preserve the insurance policy, registration certificate, driving licence, repair estimates, photographs and medical papers. Gaurav Goel, Senior Partner, Supreme Laws, adds: “An insurance claim is not merely a conversation with the insurer; it is a documented legal process. A claimant who maintains a proper paper trail is in a much stronger position if the claim later becomes contentious.”

The vehicle should ordinarily be made available for inspection or assessment before extensive repairs are carried out, particularly where the insurer requires a survey or inspection under the applicable policy terms. The policyholder should provide truthful information and the documents reasonably required for assessment of the loss. At the same time, the claimant should not blindly accept the insurer’s assessment. The policy should be examined to understand the scope of coverage, deductibles, depreciation, exclusions and other applicable conditions. If the insurer proposes a settlement amount, the claimant should carefully examine how that figure has been calculated. Advocate Tarlok Singh explains: “The amount offered by an insurance company should be examined against the actual policy coverage and the documented loss. If there is a disagreement, the policyholder should ask for the basis of the assessment and preserve the survey and settlement documents rather than relying on oral discussions.”

If an insurance claim is rejected, delayed or settled for an amount that the policyholder believes is unjustified, the matter should not simply be abandoned. The claimant should request the insurer to communicate its decision and reasons in writing. A proper review of the policy, claim documents, survey report, photographs, repair bills and correspondence can help determine whether the insurer’s position is sustainable. Where necessary, the policyholder can pursue the insurer’s internal grievance mechanism and thereafter explore the remedies available under the applicable insurance and consumer law framework. In serious accidents involving bodily injury or death, there may also be separate claims for compensation arising from the accident. Such proceedings can involve questions of negligence, contributory negligence, insurance coverage and the appropriate assessment of compensation. Legal advice at an early stage can therefore help prevent avoidable mistakes, particularly where the parties disagree about fault or the insurer contests the claim.

After a crash, act promptly but do not act carelessly. Secure medical help, preserve the accident scene, collect reliable evidence, inform the police where appropriate, notify the insurer and maintain copies of every document. Do not admit liability merely because you are shaken or pressured at the scene, and do not sign a final settlement document without understanding its consequences. Where injuries are serious, liability is disputed or an insurance claim is rejected or inadequately assessed, timely legal assistance can be crucial. The strongest accident claim is usually built not after the dispute begins, but from the evidence preserved immediately after the accident.

5 SARFAESI Mistakes Borrowers Make — And Why Delay Can Cost Them Dearly

When a borrower receives a SARFAESI notice, the first reaction is often emotional rather than legal: “The bank cannot take my property.” That assumption can be costly. The SARFAESI Act gives secured creditors a statutory route for enforcing security interests, while also providing borrowers with specific opportunities and remedies at different stages of the process. One of the biggest mistakes borrowers make is therefore ignoring the first demand notice. A Section 13(2) notice should not be treated as routine correspondence. It is the point at which the borrower should verify the outstanding amount, examine the loan account, check the security documents and identify any genuine dispute concerning the bank’s claim. A borrower who waits for possession or auction before taking advice may find that valuable time has already been lost.

The second mistake is responding emotionally instead of responding intelligently. A letter saying that the borrower is suffering financial hardship or requesting the bank to “give some more time” may not address the actual legal or factual issues in the account. If there are genuine discrepancies, they should be supported with documents and clearly presented. The third mistake is assuming that a technical defect automatically wipes out the bank’s entire claim. It does not. A borrower may identify an irregularity in possession, valuation or sale proceedings, but that does not necessarily mean the underlying debt has disappeared. The enforcement process has to be examined as a whole, including compliance with the Security Interest (Enforcement) Rules, which prescribe requirements concerning possession notices, valuation, reserve price and sale of immovable secured assets.

The fourth mistake is waiting until the property is advertised for auction before exploring legal remedies. Once possession and sale formalities have progressed, the borrower may have to act quickly and within the applicable statutory framework. Section 17 provides a remedy before the Debts Recovery Tribunal against measures taken under Section 13(4). At the same time, borrowers should carefully distinguish between a genuine legal challenge and an attempt merely to postpone repayment. Gaurav Goel, Senior Partner, Supreme Laws, says: “A borrower should not mistake the availability of a legal remedy for a licence to ignore a genuine financial liability. Where the bank has followed the prescribed procedure, the borrower must have a substantive and legally sustainable basis for opposing enforcement.” He further cautions that litigation without a realistic strategy can sometimes reduce the borrower’s options rather than improve them.

The fifth mistake is failing to think about resolution alongside litigation. A borrower may have a legitimate objection to a particular enforcement step and still need to address the underlying financial liability. Depending upon the facts, discussions concerning repayment, restructuring or a negotiated settlement may therefore deserve consideration alongside appropriate legal proceedings. From the bank’s perspective, recovery of secured dues is not merely an administrative exercise; it is the enforcement of a contractual and statutory right, subject to compliance with law. The Rules require, among other things, valuation by an approved valuer and fixation of a reserve price before sale of an immovable secured asset. Gaurav Goel adds: “Banks cannot be expected to keep recovery proceedings indefinitely in abeyance when public or institutional funds remain outstanding. A borrower who genuinely wants to protect the property should act early, place a credible proposal before the lender where appropriate, and pursue only those legal objections that can withstand scrutiny.” The practical lesson is simple: do not ignore SARFAESI, do not rely solely on technicalities, and do not wait until the auction date to decide what to do.


The Forgotten Victims in Rent Disputes: Elderly and Women Landlords Deserve Equal Justice

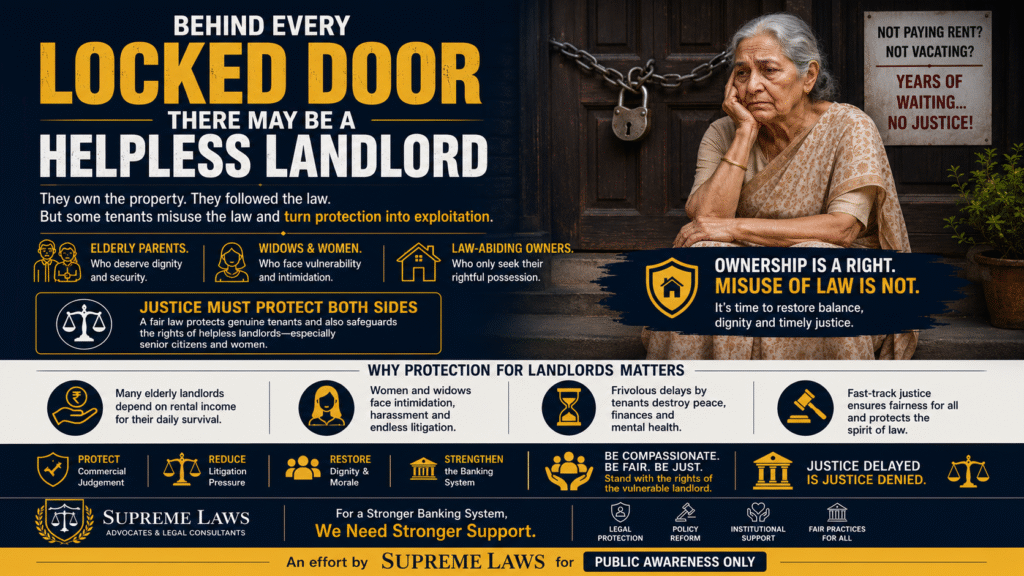
For decades, India’s tenancy laws have rightly sought to protect tenants from arbitrary eviction and unfair treatment. However, this noble objective has also created an unintended consequence. Across the country, countless elderly parents, widows, and single women who own residential or commercial property are finding themselves trapped in lengthy legal battles simply to recover possession of their own premises. While tenant protection remains an essential pillar of social justice, the law must also recognize that landlords can be equally vulnerable.

Many senior citizens depend entirely on rental income to meet their daily expenses or require their property for personal occupation after retirement. Unfortunately, some tenants misuse legal procedures by withholding rent, refusing to vacate, and prolonging litigation for years. Gaurav Goel, Senior Partner, Supreme Laws, observes, “The law must distinguish between protecting a genuine tenant and rewarding deliberate misuse of legal safeguards. The constitutional right to own and enjoy property cannot be defeated through endless procedural delays, particularly when the landlord is an elderly person or a woman in genuine need.” Justice loses its meaning when the rightful owner spends years fighting merely to use what already belongs to them.

The financial and emotional burden of such disputes is often unbearable. Elderly landlords frequently exhaust their savings on litigation, while widows and women living alone are compelled to endure unnecessary stress and uncertainty. In many cases, these individuals are not wealthy investors but ordinary citizens whose property represents their life’s earnings. When legal proceedings become excessively prolonged, the hardship extends far beyond financial loss—it affects dignity, security, and peace of mind.

Indian courts have consistently recognized that tenancy does not confer ownership and that a landlord’s bona fide requirement deserves legal protection. Advocate Tarlok Singh states, “A tenancy is a contractual relationship, not a permanent right over another person’s property. The legal system must ensure that vulnerable landlords are not compelled to sacrifice their rights because of avoidable procedural delays.” A legal framework that protects both tenants and landlords with equal fairness strengthens public confidence and promotes responsible tenancy rather than conflict.

The need of the hour is a balanced approach. Genuine tenants must continue to receive protection against arbitrary eviction, but habitual defaulters and those who misuse legal provisions should not be permitted to exploit the justice delivery system. Expedited proceedings for disputes involving senior citizens and women landlords, stricter enforcement of eviction orders, and deterrence against frivolous litigation would help restore the equilibrium that tenancy laws originally intended to achieve. As Gaurav Goel, Senior Partner, Supreme Laws, aptly remarks, “Protecting vulnerable landlords is not contrary to tenant welfare. A fair legal system safeguards lawful possession, discourages abuse of process, and ensures that justice is delivered within a reasonable time.”

A compassionate legal system cannot afford to recognize vulnerability only on one side of a dispute. The elderly father waiting to return to his own house, the widow relying on rental income for survival, and the woman seeking possession of her inherited property deserve the same protection that the law extends to tenants. Justice is truly meaningful only when it safeguards both the right to shelter and the right to peaceful ownership, ensuring that neither is sacrificed at the cost of the other.


Too Many Hats, Too Little Banking

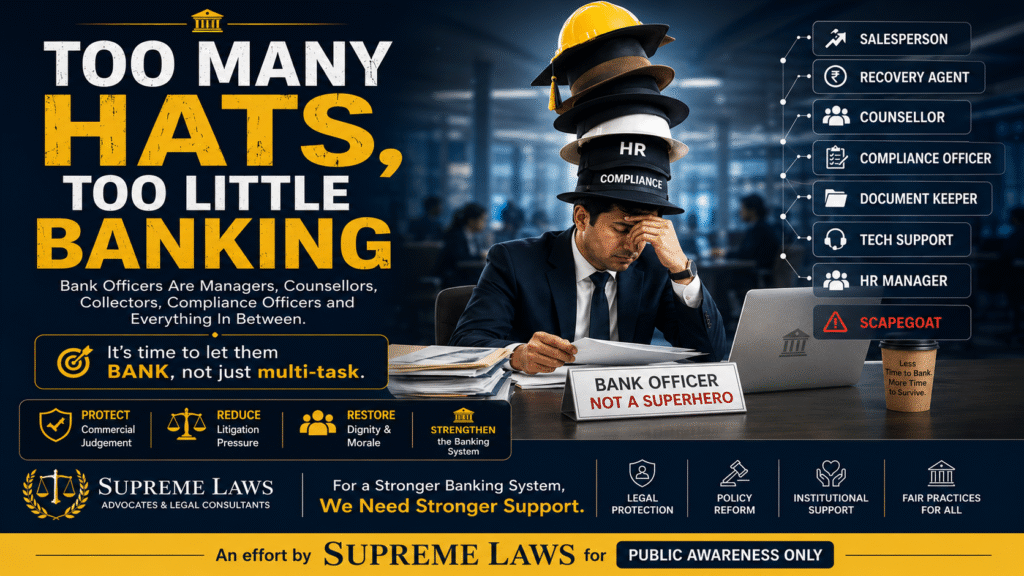
India’s banking sector has become the backbone of economic growth, yet its efficiency is increasingly undermined by the growing burden of non-banking responsibilities placed on bankers. Besides mobilizing deposits, assessing creditworthiness, and managing financial risks, they are expected to undertake gold evaluation, property and land assessment, title verification, machinery valuation, insurance coordination, legal compliance, recovery proceedings, and extensive documentation. Many of these technical assignments should be handled by qualified valuers, engineers, and legal experts. Diverting bankers from their core responsibilities results in slower customer service, delayed loan sanctions, reduced branch efficiency, mounting workplace stress, declining productivity, and higher operational risks.

The consequences of this misplaced allocation of work are evident across the banking system. Bank employees are often held accountable for technical decisions beyond their professional expertise, such as gold valuation, land assessment, construction inspection, or market valuation. These tasks require specialized knowledge and independent professional judgment. Performing them increases the risk of inaccurate valuations, fraud, legal disputes, and financial losses. Simultaneously, business targets and regulatory obligations create additional pressure, reducing productivity and customer confidence. Instead of concentrating on prudent lending and relationship management, bankers become multitasking administrators performing duties that specialized professionals could handle more effectively.

A practical solution lies in redefining the operational framework through policy intervention by the Government of India, the Reserve Bank of India, and banking regulators. A nationwide network of accredited professionals should undertake specialized functions such as gold valuation, property assessment, engineering inspections, and legal due diligence. Banks should rely exclusively on certified valuers, engineers, surveyors, and legal experts operating under statutory accountability. Digital platforms can streamline report submission and verification, while periodic audits, performance ratings, and strict penalties ensure transparency. This specialization would reduce operational risks and enable bankers to focus on credit analysis, customer service, fraud prevention, and portfolio management.

The successful implementation of these reforms requires a phased and coordinated policy approach. The Ministry of Finance, RBI, Indian Banks’ Association, and banks should jointly issue uniform operational guidelines clearly defining the responsibilities of bankers and external experts. Banking manuals should prohibit branch officials from independently conducting technical evaluations where certified professionals are available. Pilot projects can refine procedures before nationwide implementation, supported by digital integration with accredited service providers. Regular monitoring through indicators such as processing time, credit quality, customer satisfaction, and employee productivity will ensure measurable success. Allowing bankers to focus exclusively on banking will strengthen operational efficiency, improve lending quality, reduce avoidable risks, and support sustainable economic growth.


Disclaimer

As per the rules of the Bar Council of India, we are not permitted to solicit work or advertise in any manner. By proceeding further and clicking on “I Accept” below, the user acknowledges that the transmission, receipt or use of the information on our website does not tantamount to solicitation, advertisement, inducement or personal communication of any sort for and on behalf of the Firm so as to create an attorney-client relationship.

The information provided herein should not be interpreted as legal advice, for which the user must make independent inquiries. Whilst every effort has been taken to ensure the accuracy of the contents of this website, Supreme Laws disclaims all liability arising from reliance placed by the user or any other third party on the information contained therein.